 By
Two working parents often juggle calendars, school events, and paid work, which leaves very little room for money conversations. The result is usually a pattern of quick decisions, last-minute worries, and occasional arguments about things nobody had time to discuss. A short monthly check-in can replace that pattern with a calm routine. This article offers a simple agenda, a repeating time slot, and a few honest questions that keep the conversation productive. Everything here is general guidance, so consult a qualified adviser for decisions with significant tax, legal, or debt consequences.
Choose a Repeating Time Slot
The first step is to pick a time that both adults can protect. A quiet evening after the children are settled, or a relaxed weekend morning, usually works well. Put the slot in a shared calendar with a clear title, so it is treated like any other appointment. Readers may also want to visit Realestateguidance.org. Keep the meeting short, ideally a focused session that ends before either person feels drained. Consistency matters more than length. A brief meeting that happens every month is far more useful than a long session that gets postponed again and again.
Gather the Same Documents Each Time
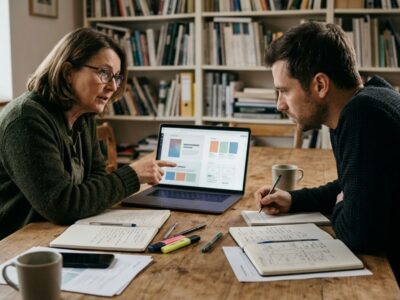
Use a consistent set of documents so that every check-in starts from the same place. A simple setup might include the current balance across shared accounts, a list of upcoming bills, and the planned spending summary for the coming month. Printing or saving these items in one folder reduces the search time on busy evenings. You can also visit sinolandquality.com for more reading. When the documents are familiar, the conversation moves faster, and both adults can focus on decisions rather than on finding information. Keep the folder in a place both adults can reach easily, and add a short note at the front listing any items still missing. This small step prevents the common situation where a meeting starts and one person realizes the key figure is only in an email.
Ask Three Honest Questions
Each check-in works best when it answers a few clear questions. What did we spend more than we planned, and why? What costs are coming up that we have not yet prepared for? Is there one change that would make next month easier? Keep the questions neutral and avoid searching for someone to blame. For a related read on this site, see Checking Whether a Side Hustle Fits Your Weekly. Honest answers are useful only when they lead to a concrete action, such as moving money to a reserve or adjusting a weekly routine. It helps to take turns asking the questions, so that neither person feels cross-examined. One adult can read a question aloud while the other notes the answer on the shared document. Keep track of decisions in a single line each, and avoid long debates in the moment. If a topic needs more thought, park it for the next session with a clear note so it does not return unannounced.
Follow this agenda in order, so the meeting stays focused:
1. Confirm the current balances and the bills due in the next month.
2. Compare last month’s plan with what actually happened.
3. Note any unexpected costs and whether they are likely to repeat.
4. Agree on one practical change for the coming month.
5. Confirm who will handle each payment and when.
Plan for the Next Month’s Surprises
Surprises are a normal part of family life. A birthday party invitation, a broken appliance, or a school trip request can appear with little warning. During the check-in, set aside a modest amount for these unplanned costs, and decide in advance how the family will respond. This removes the stress of making a decision under pressure. When an unexpected cost appears, both adults can refer to the agreed approach rather than starting the discussion from zero. Over several months, the buffer becomes a quiet source of confidence. A useful exercise is to list the few surprises that have happened most often over the last year. Many families notice that school events, seasonal clothing needs, and small repairs appear again and again. Once those patterns are visible, the buffer can be sized to match real experience rather than guesswork, and the couple can feel more secure about the months ahead.
A monthly check-in is not a meeting for judging each other. It is a short, regular way to keep two busy adults aligned on money, school costs, and family priorities. Start small, keep the same format, and adjust as the children grow. If you face debt, a changed income, or a complicated tax situation, arrange time with a qualified professional who can review your specific position.